You’ve Spent a Lifetime Saving for Retirement.
Three Things Determine Whether It Lasts: Markets, Taxes, and Time.
Our signature Bucket Strategy coordinates your income, investments, taxes, and legacy goals, because after decades of saving, you’ve earned a plan, not just a portfolio.
Any of These Feel Familiar?
You don’t have to see yourself in every statement. But if a few of these describe where you are today, you are exactly the kind of person we help navigate retirement with greater clarity and confidence.
I have investments, but I don’t have a real plan for turning them into income.
I’m within 5 to 10 years of retirement, or already retired.
I don’t want one bad market to damage years of disciplined saving.
I would rather have my retirement decisions coordinated in a structured process than try to piece retirement together alone.
You do not have to piece together retirement income, taxes, Social Security, Medicare, and market risk on your own.
See if a retirement income strategy session is the right next step
The Money Cycle
The Importance of the Preservation Phase
The Preservation phase is what protects you through the Critical Window. This period is crucial for protecting your assets and preparing for market uncertainties. No one knows when a bull market will end or the next bear market will begin. If you're nearing retirement, now is the time to prepare and ensure that your strategy is aligned with your future needs.
"The biggest mistake pre-retirees and some accumulation specialist advisors make is overlooking the Preservation Phase of the Money Cycle." Mike F. Moss, Senior Financial Consultant
5 to 7 Years Before Retirement
Through 10 Years After

The strategy is growth.
The Climb.
Purpose of the Phase
The longest phase of the Money Cycle, typically 30 to 40 years. Save consistently. Stay invested. Let time and your next paycheck work in your favor.
During accumulation, market declines are often opportunities. Your next contribution buys more shares while prices are lower.

The strategy is preservation.
The Critical Window.
Purpose of the Phase
During this window, we position a portion of your assets to help replace your paycheck. These are structured for stability and liquidity because they're needed first.
It's also the phase many retirement plans overlook, even though it may be the most important.

The strategy is dependable retirement income.
The Descent.
Purpose of the Phase
Your portfolio is now expected to replace your paycheck, potentially for 30 years or more.
In Distribution a market decline is no longer a buying opportunity. There's no new paycheck arriving to buy more shares, and your investments now have a different job.
Review key retirement income terms
Retirement problems often begin when yesterday's accumulation strategy is used for today's income needs.
What's Needed Is a Different Kind of Investment Strategy
Is Your Advisor a Climber or a Guide for the Descent?
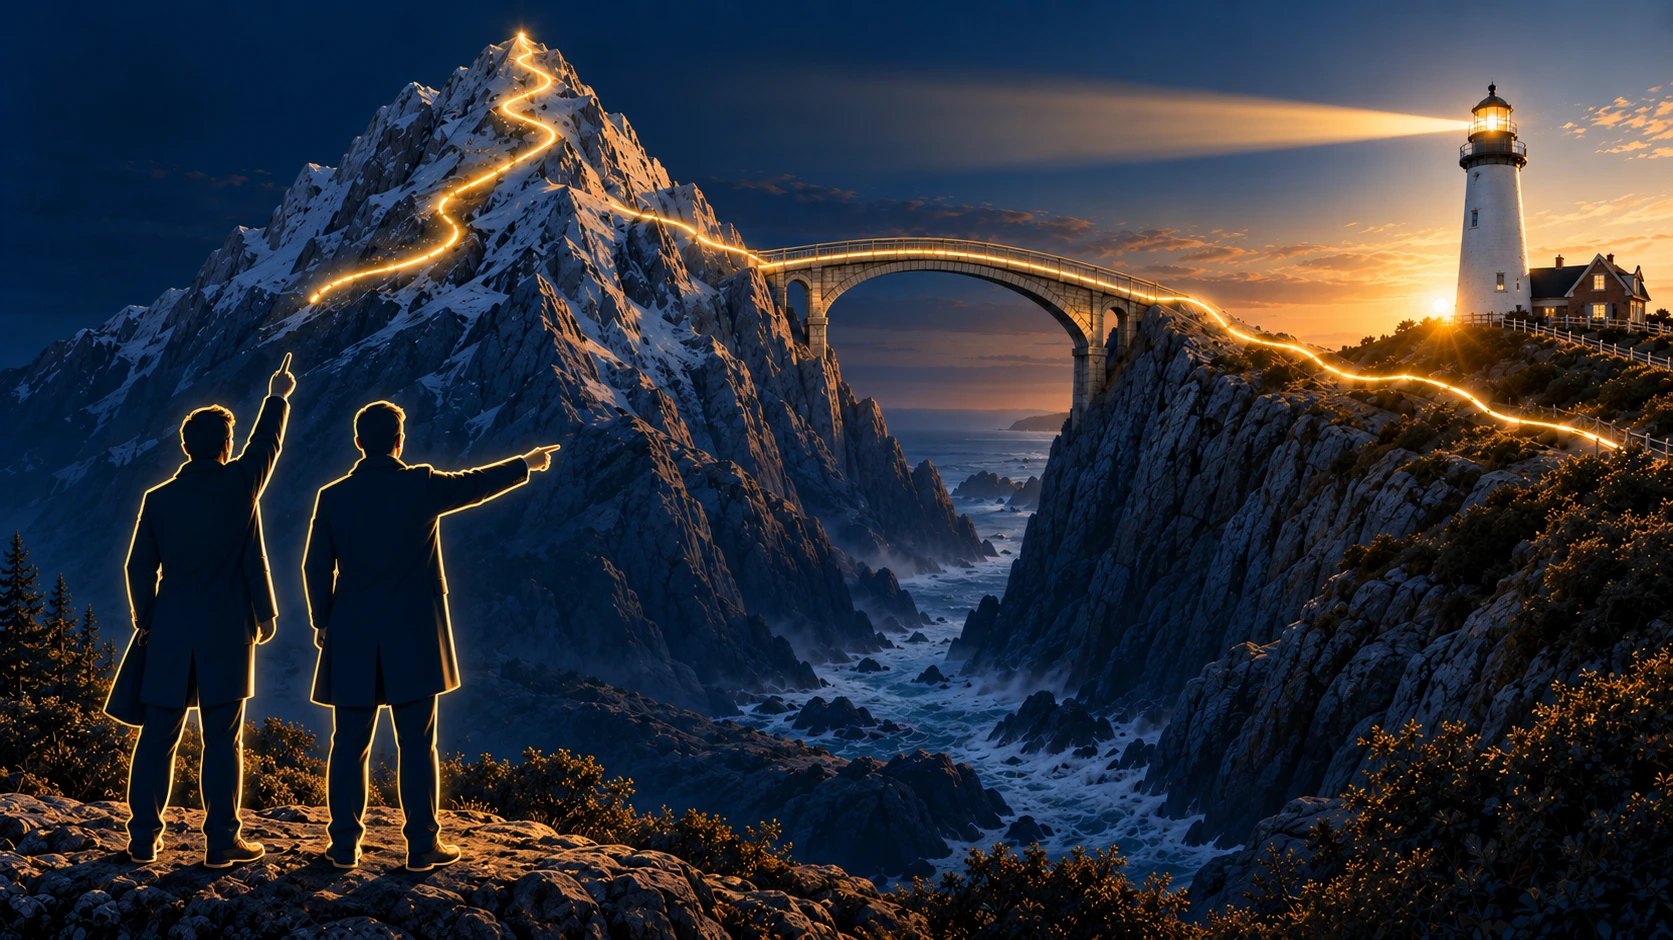
The financial industry was largely built to serve accumulation. Its tools, products, and strategies were developed for people still climbing. That's not wrong. It's simply a different specialty.
The Advisor You Needed Then May Not Be the Advisor You Need Now
If your current advisor is using the Preservation Phase of the Money Cycle, specifically addressing where your first years of retirement income will come from, how withdrawals will be sequenced, and how taxes will be coordinated, you are likely working with a Distribution Specialist.
If the conversation is still about growth, average returns, and staying invested, with no meaningful discussion of the Preservation Phase, they are likely an Accumulation Specialist. Both play an important role. The question is whether the role you need now is the one they specialize in.
The Critical Question
How will we deal with a bear market when, not if, it happens, before or during retirement?
The accumulation and distribution portfolios may look the same. They are not. One rewards patience and growth. The other requires structure and protection. Most people are never taught the difference.
Decades of good investment advice can get you to retirement. But a portfolio alone will not get you through it. What is required is a different kind of planning entirely.
The Bucket Strategy
A Common Sense Approach to Managing Income
Because not every dollar should be treated the same. The Bucket Strategy simply gives every dollar the right job.
Your retirement savings were built one way. Living from them requires a different strategy.
During your working years, the primary goal is accumulation. In retirement, the challenge changes. You need a strategy for turning savings into income while still giving longer-term dollars time to grow.
The Bucket Strategy organizes retirement dollars by purpose and timeline, so near-term income, future income, and long-term growth are not all forced to do the same job at the same time.
Explore the Bucket Strategy Page⚠ Hypothetical illustration only. Not representative of any actual investment or account. All investing involves risk including loss of principal.
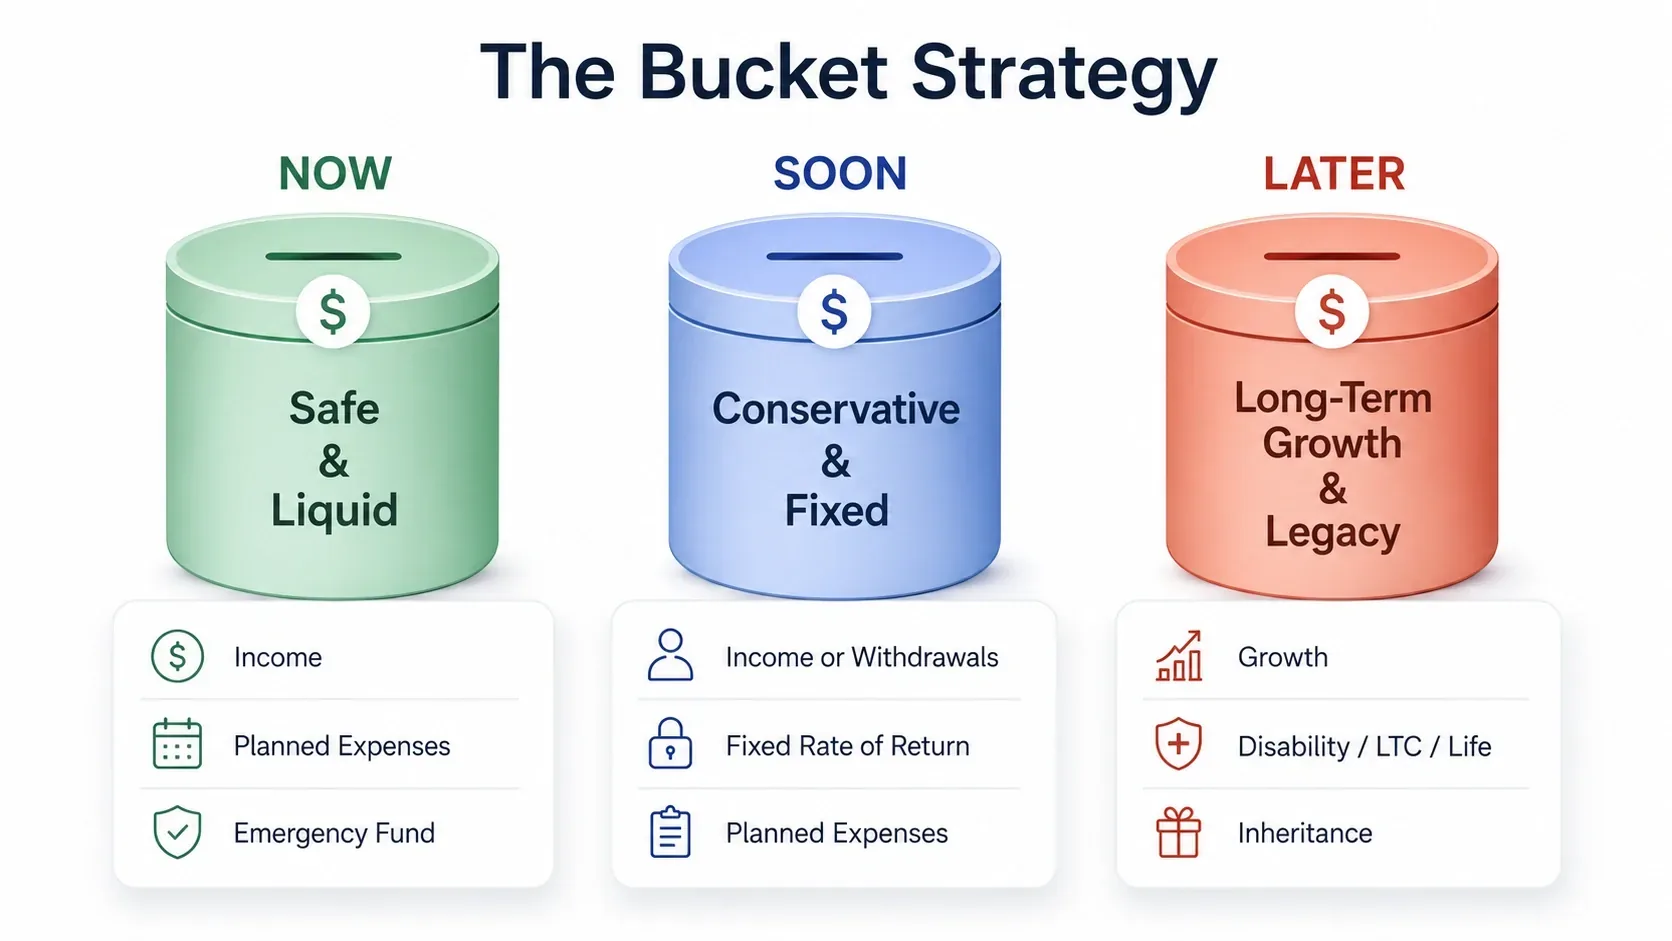
The goal is not just to own a portfolio. The goal is to know how that portfolio will support your retirement life.
Frequently Asked Questions
What happens to my income if the market drops?
The Bucket Strategy separates near-term income from growth assets, so a market decline doesn't directly impact your monthly income.
What does the Income Strategy Session phone call look like?
It is a relaxed, no-obligation 20 to 30 minute phone call focused on understanding your situation, your questions, and whether our planning process may be a good fit. We explain how we work, talk through your most important retirement concerns, and help you decide whether a next step makes sense.
Who is an ideal client for Lighthouse Financial Strategies?
We work best with age 50+ pre-retirees and retirees who want their major retirement decisions coordinated through one ongoing planning process.
How is retirement income planning different from investment management?
Investment management focuses primarily on how assets are invested. Retirement income planning goes further by coordinating when and where income will come from, how taxes may affect withdrawals, how near-term spending needs are supported, and how the investment strategy connects to the rest of your retirement plan.
Schedule a Strategy Call
A relaxed, no-pressure 20 to 30 minute phone call to learn about your situation and see whether our retirement income planning process may fit your needs.
The life your plan is built to protect.
You do not need to have every account statement in hand or all of your financial information organized before the call. Most people come to us because several retirement decisions have started to feel connected, complicated, and too important to guess at. The first conversation is simply about understanding where you are and whether our process may be useful.
Your situation
You are age 50+, retired or within 5 to 10 years of retirement, and want a clearer plan for turning savings into income.
What you have
You have approximately $1 million or more in retirement savings and investable assets and want them coordinated within a broader retirement plan.
What you want
You want an ongoing planning relationship and a structured process, rather than trying to sort through complex retirement decisions by yourself.
Who It May Not Be For
You prefer to manage everything yourself with no outside guidance. You are mainly looking to actively trade or time the market. You are not yet building toward retirement.
How it works
We will ask about your situation, walk through your most pressing questions, and give you an honest picture of what working together could look like.
WHAT YOU LEAVE WITH
A Clearer Sense of What Deserves Attention Next
The Income Strategy Session is not a complete financial plan. It is an initial conversation designed to help you better understand the questions your retirement strategy may need to answer.
After the call, you should have a clearer sense of:
How Your Investments Support Income
Whether your investments appear to be organized around future retirement income needs, or are simply invested without a defined withdrawal structure.
Which Decisions Deserve Attention First
Which retirement questions may be most urgent and which can be addressed over time.
Whether Important Decisions Are Being Coordinated
Whether taxes, Social Security, Medicare, investment withdrawals, and survivor considerations appear to be working together.
Whether Our Process May Fit Your Situation
Whether the Bucket Strategy and Beacon 360 Process appear appropriate for the kind of retirement decisions you are facing.
Even if we do not work together, the goal is for you to leave with a clearer understanding of what deserves attention next.
Having difficulty using the online scheduler? Call or email Mike to schedule your Income Strategy Session.
Mike Moss
Senior Financial Consultant
Lighthouse Financial Strategies
Boardman, Ohio
Phone
330-758-7545
Based in the Mahoning Valley and serving Boardman, Canfield, Poland, Austintown, Youngstown, Warren, and Western Pennsylvania, we also work virtually with retirees across the country who want a clear, dependable retirement income strategy.